SS Retail IPO - My Quick Take
I went through the RHP of
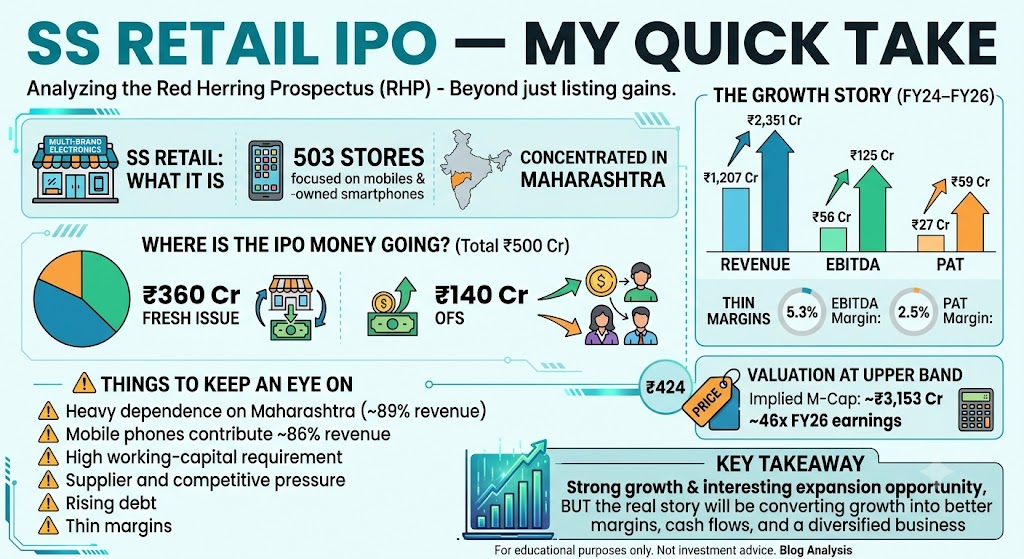
SS Retail to understand what’s actually behind the IPO, rather than looking at it only from the listing-gain perspective.SS Retail is a multi-brand retailer focused mainly on
mobiles, electronics and pre-owned smartphones, with
503 stores, largely concentrated in Maharashtra.The growth story definitely stands out:
Revenue: ₹1,207 Cr → ₹2,351 Cr
EBITDA: ₹56 Cr → ₹125 Cr
PAT: ₹27 Cr → ₹59 Cr
(FY24–FY26)But there’s another side to the story —
margins are still quite thin, with EBITDA margin at 5.3% and PAT margin at 2.5%.
Where is the IPO money going?Out of the ₹500 Cr issue:
•
₹360 Cr Fresh Issue — mainly for working capital and store expansion
•
₹140 Cr OFS — goes to existing shareholders
Things I would keep an eye on• Heavy dependence on Maharashtra — ~89% of revenue
• Mobile phones contribute ~86% of revenue
• High working-capital requirement
• Supplier and competitive pressure
• Rising debt
• Thin marginsAt the upper price band of ₹424, the implied market cap is around
₹3,153 Cr, or roughly
46x FY26 earnings. So, at this valuation,
future growth and execution become very important.
My key takeawayThe business has shown
strong growth and an interesting Tier-II/III expansion opportunity, but for me, the real story going forward will be whether SS Retail can convert that growth into
better margins, stronger cash flows and a more diversified business.
For educational purposes only. Not investment advice.

 Launch your Graphy